Showing posts with label European Union. Show all posts
Showing posts with label European Union. Show all posts
Thursday, April 14, 2016
Great Paper on the New Keynesian model
As I was scourging through interesting papers, I found a very interesting paper written by Cohen-Setton, Hausman and Wieland on the New Keynesian model. Within the contents of the paper, they discuss the New Keynesian model and it's effect on supply-side shocks in depressed economies. They utilized a very interesting example in France and its economy after a special measure where they had lifted the gold standard and set interesting economic measures. The results are quite fascinating and the paper goes into quite detail utilizing time series and a fantastic model to describe what had happened in detail. I'm still reading the paper, but it looks like they have found the key to the current debate over structural reforms within both the United States and the European Union. By utilizing these structural reform measures that were recommended before, the example shows that it doesn't particularly work very well in times of rare financial crises. A good read for anyone who is interested in these pressing matters, along with observing the model that they had utilized.

Friday, March 20, 2015
Couple of Interesting Articles That I Have Been Reading
It has been a while since I have last posted here and I have been relatively busy the last couple of weeks. Here are the links to several interesting articles that I have been reading on top of the numerous economics journals and numerous other magazines I have been rummaging through the last couple of weeks:
1. An article by Steve Mufson in the Washington Post on possible Federal Reserve signals that a rate hike is possible. Here's another article on this particular subject written by John Cassidy of the New Yorker. It has been an interesting signal by the Federal Reserve, headed up by Janet Yellen, that they will eventually raise interest rates, but there are conflicted signals on what the economic outlook is. I forsee a not-so-great economic outlook at least for the next couple of quarters.
2. Matt Rognlie's thoughts on Thomas Piketty's observations posted on the Brookings Institution website. Quite an interesting article that he has written and here's the full copy of his work posted again on the Brookings Institution website. He is currently a PHD down the street from where I live at the Massachusetts Institute of Technology and in this article, he comes up with interesting data that somewhat backs up Thomas Piketty's thesis, but refutes it in the most part. He should be one economist to be followed in the coming years as he publishes more works.
3. A charming German couple goes to the former capital of Greece and pays off their portion of the "German World War 2 reparations" to Greece. This is quite a lovely move by the couple on a very serious issue of Greece threatening Germany with seizing German property if they do not pay long overdue World War 2 reparations, but it just shows the desperation of a completely bankrupt nation with no money left in the bank.
4. An interesting article that actually just came out on my news feed approximately 30 minutes ago. It talks about how debt will hit emerging economies. As predicted by an earlier blog post of mine, a potential economic crisis will start when some of these emerging economies see growth slow, debt accumulate and possible defaults happen.
1. An article by Steve Mufson in the Washington Post on possible Federal Reserve signals that a rate hike is possible. Here's another article on this particular subject written by John Cassidy of the New Yorker. It has been an interesting signal by the Federal Reserve, headed up by Janet Yellen, that they will eventually raise interest rates, but there are conflicted signals on what the economic outlook is. I forsee a not-so-great economic outlook at least for the next couple of quarters.
2. Matt Rognlie's thoughts on Thomas Piketty's observations posted on the Brookings Institution website. Quite an interesting article that he has written and here's the full copy of his work posted again on the Brookings Institution website. He is currently a PHD down the street from where I live at the Massachusetts Institute of Technology and in this article, he comes up with interesting data that somewhat backs up Thomas Piketty's thesis, but refutes it in the most part. He should be one economist to be followed in the coming years as he publishes more works.
3. A charming German couple goes to the former capital of Greece and pays off their portion of the "German World War 2 reparations" to Greece. This is quite a lovely move by the couple on a very serious issue of Greece threatening Germany with seizing German property if they do not pay long overdue World War 2 reparations, but it just shows the desperation of a completely bankrupt nation with no money left in the bank.
4. An interesting article that actually just came out on my news feed approximately 30 minutes ago. It talks about how debt will hit emerging economies. As predicted by an earlier blog post of mine, a potential economic crisis will start when some of these emerging economies see growth slow, debt accumulate and possible defaults happen.
Thursday, February 19, 2015
Greek Finance Minister, Game Theory and the Big Showdown
In an earlier and rather detailed blog post, I had talked about the Greek debt situation and the stories that surround it. I have decided to post another blog entry primarily about the game theory and the Greek financial minister, Yanis Varoufakis, especially due to his showdown with Germany and the developing crisis in the European Union. The news has just hit today that Germany has rejected the Greek proposal to extend the bailout program by an additional 6 months. The Syriza government had been under enormous pressure by both the European monetary authorities and the officials of various European financial ministries to continue the bailout program despite rejecting the program itself. This article will try to explain the background of the Greek Finance Minister, Yanis Varoufakis, in more detail, but also will go deeper into how his research interest in economics, Game Theory, has also come into play during the midst of this big showdown between the new leftist Syriza government and the European monetary authorities.
The Greek Finance Minister, Yanis Varoufakis, has now become very well-known within the politics of the continent due to his showdown with the European monetary authorities and his penchant for his plain dress combined with a defiant attitude towards what the Troika had committed to his native country of Greece, but also within the economic world with his unorthodox economic views. In two articles, one commentary article written by him in the Guardian newspaper several years back and another article on the left-liberal activist site, CounterPunch, it illustrates a man who is determined not to just change the policies of austerity and liberal capitalism in Greece, but throughout the entire European Union. In the first article, we can picture a man who was trained within the confines of mainstream economics, but had defined himself in 2012 as a Marxist. He did not describe himself as the prototypical Marxist, but one that is committed to changing the economic dimensions within Europe. In the article, he described the economics within the continent as one that is committed to the form of neoliberal capitalism, but his progressive politics of the left will be rejuvenated from the doldrums to saving European capitalism. From this article, we can see a man who is dedicated to the leftist ideology of changing Europe and the economics within the continent towards one that is certainly socialist both in policy and in application.
The second article describes Mr. Varoufakis' plans in detail about changing the dynamics of the European economic system into one that promotes growth and not austerity. The tone of the article also described how a previously unknown Greek economist had stared down the monetary bureaucrats of the European Union and sent some of them scared. It could be best said that Varoufakis had utilized some of his training as an economist, especially in the arts of game theory, to give what little the Greek government had previously into an enormous advantage over the people at the Eurogroup. For those, who are not familiar with Game theory, here's a short BBC article that explores the dimensions of the games (which include possible applications of zero-sum games and of the prisoner's dilemma) that Greece has been playing with the Troika, the Eurogroup and other European countries like Germany. He also has written an article in the New York Times on the big showdown with the European monetary authorities, which includes Germany and Angela Merkel. In the article, he lambasted how they "should not" be utilizing game theory with each other over the debt deal, but should be best focused on how to provide the average population a way out of desperate poverty and destitution. It does make a lot sense to anyone who has read his article, but Varoufakis has been utilizing all sorts of strategies that are based on game theory in dealing with the European monetary authorities! In an article by a popular Forbes contributor, Tim Worstall, there's absolute no room for game theory here! Regardless of whether most people have agreed with Greece's accession into the Eurozone or with the following policy decisions that the European monetary authorities have undertaken, Greece and the European Union are in trouble.
Exactly how much trouble are the European Union, Greece and the Eurozone in? A good question might be to ask about the other debt troubles that various European nations such as Spain, Italy, Portugal and even France have in the future. Germany is not even immortal with its enormous debt burden that it has also managed to start decreasing in the last couple of years, but another crisis could exacerbate the debt levels even in Germany which are already alarmingly high. I strongly disagree with a recent Economist article on how Greece could have made the Eurozone work better. Greece could not have made the Eurozone work better, as there are numerous other economies that are facing similar problems as Greece. I believe that with the Greek Finance Minister's dangerous moves may put the European Union and the Eurozone at its brink, but there is also ample room for finding a balance between the views of both Germany and Greece. By rejecting each other's counter-proposals, they are putting the world economy at risk with their latest proposals. Worried Greek depositors and international investors will now brace for the final showdown between Greece and the European monetary authorities. Let's hope we don't wake up to see an avoidable financial crisis.
The Greek Finance Minister, Yanis Varoufakis, has now become very well-known within the politics of the continent due to his showdown with the European monetary authorities and his penchant for his plain dress combined with a defiant attitude towards what the Troika had committed to his native country of Greece, but also within the economic world with his unorthodox economic views. In two articles, one commentary article written by him in the Guardian newspaper several years back and another article on the left-liberal activist site, CounterPunch, it illustrates a man who is determined not to just change the policies of austerity and liberal capitalism in Greece, but throughout the entire European Union. In the first article, we can picture a man who was trained within the confines of mainstream economics, but had defined himself in 2012 as a Marxist. He did not describe himself as the prototypical Marxist, but one that is committed to changing the economic dimensions within Europe. In the article, he described the economics within the continent as one that is committed to the form of neoliberal capitalism, but his progressive politics of the left will be rejuvenated from the doldrums to saving European capitalism. From this article, we can see a man who is dedicated to the leftist ideology of changing Europe and the economics within the continent towards one that is certainly socialist both in policy and in application.
The second article describes Mr. Varoufakis' plans in detail about changing the dynamics of the European economic system into one that promotes growth and not austerity. The tone of the article also described how a previously unknown Greek economist had stared down the monetary bureaucrats of the European Union and sent some of them scared. It could be best said that Varoufakis had utilized some of his training as an economist, especially in the arts of game theory, to give what little the Greek government had previously into an enormous advantage over the people at the Eurogroup. For those, who are not familiar with Game theory, here's a short BBC article that explores the dimensions of the games (which include possible applications of zero-sum games and of the prisoner's dilemma) that Greece has been playing with the Troika, the Eurogroup and other European countries like Germany. He also has written an article in the New York Times on the big showdown with the European monetary authorities, which includes Germany and Angela Merkel. In the article, he lambasted how they "should not" be utilizing game theory with each other over the debt deal, but should be best focused on how to provide the average population a way out of desperate poverty and destitution. It does make a lot sense to anyone who has read his article, but Varoufakis has been utilizing all sorts of strategies that are based on game theory in dealing with the European monetary authorities! In an article by a popular Forbes contributor, Tim Worstall, there's absolute no room for game theory here! Regardless of whether most people have agreed with Greece's accession into the Eurozone or with the following policy decisions that the European monetary authorities have undertaken, Greece and the European Union are in trouble.
Exactly how much trouble are the European Union, Greece and the Eurozone in? A good question might be to ask about the other debt troubles that various European nations such as Spain, Italy, Portugal and even France have in the future. Germany is not even immortal with its enormous debt burden that it has also managed to start decreasing in the last couple of years, but another crisis could exacerbate the debt levels even in Germany which are already alarmingly high. I strongly disagree with a recent Economist article on how Greece could have made the Eurozone work better. Greece could not have made the Eurozone work better, as there are numerous other economies that are facing similar problems as Greece. I believe that with the Greek Finance Minister's dangerous moves may put the European Union and the Eurozone at its brink, but there is also ample room for finding a balance between the views of both Germany and Greece. By rejecting each other's counter-proposals, they are putting the world economy at risk with their latest proposals. Worried Greek depositors and international investors will now brace for the final showdown between Greece and the European monetary authorities. Let's hope we don't wake up to see an avoidable financial crisis.
Sunday, February 8, 2015
The Greek Debt Situation, the Troika, Syriza and Few Thoughts
As eyes of the world has turned towards the recent developments in Greece, I can admit that this will be an interesting period of time for Greece and the other member states of the European Union. Following the election of Syriza in the latest election, the leader of the Syriza party, Alex Tsipras, has promised the Greeks an end to the crippling austerity that the Greeks have faced ever since the start of the European debt crisis in 2009. The party aims to boost economic growth through stimulating the depressed Greek economy through Keynesian policies that will the new Syriza government promises to generate economic growth and to promote "social solidarity". What has really shocked the markets lately is Syriza's promise to stop negotiating with the Troika that consists the IMF, the European Central Bank and the European Union. The government has promised to return to the government-heavy policies of the past and to negotiate a write-off in Greek government debt. The decisive action in the economic and the political policies of the Marxists and the Keynesians that make up the intellectual leadership for the now ruling Syriza government has ran into a lot of controversy with the mainstream economic institutions that has been bailing out the Greek government and the Greek economy. In this particular blog post, I can hopefully explain the Greek situation in more details, but also impart my opinion on the state of this interesting situation that has been developing in Greece and the European Union.
Debt Situation Background and the Economic Crisis
The debt crisis in Greece had started even before the 2007-2008 Global Financial Crisis with the entrance of Greece into the Eurozone and the overspending that occurred during the Olympics was blamed for the current debt crisis that had its seeds all the way back in 2004. While the Olympic Games was one of the many financial debacles that the Greek government has had in the last two decades, I would say it compares nowhere to the other pressing problems that led up to their debt implosion that occurred after the Global Financial Crisis.
A combination of a corrupt government bureaucracy that struck shady back room deals, a culture of endemic tax evasion and a burdensome public sector led to one of the most serious debt crises that any country has faced. It has been said that the corruption of Greek officialdom led Greece into the Eurozone by utilizing the services of Goldman Sachs to make their debt situation comfortable enough for the not as corrupt European bureaucrats to let Greece into the European Union. The mistake of letting one of the most corrupt nations in Europe to enter the Eurozone was compounded by the fact that much of this debt could have avoided if Greece undertook an immense political restructuring program that changed the way politics in Greece had been operating. From the bribes that the officials had extracted from the Greek taxpayers in order to bribe corrupt European Union officials to the bribes that Greek political parties had handed out in public sector jobs led to one of the worst possible economic environments in all of Europe. The public also engaged in one of the most institutionalized tax evasion schemes in the world. Here are two articles that explain the tax evasion problem that had plagued Greece: One published by the Economist and another by the New Yorker. The Greeks had also simply been living way beyond their means for a long time with the government deficit financed growth and when the financial crisis had hit the country, the entire corrupt Greek political and economic system fell apart.
The US economic crisis caused a huge breakdown in the global debt pyramid that had partially relied on the US mortgage-backed securities for further growth. With the entire debt pyramid collapse, there it unleashed an onslaught of bad debt and bad loans. It triggered a tidal wave of debt crises around in Europe and the worst basket case example in the Hellenic country of Greece. Countries like Greece that had largely been living beyond their means through cheap interest rates that the Eurozone had brought. Through years of unnatural interest rates and a horribly mismanaged national economy, Greece paid the ultimate price for being in the same economic zone with countries like Germany. The Greeks had to be bailed out several times and here's an article from 2012 that described the situation in Greece 3 years ago.
The International Lenders and Greece
The 'Troika' of the International Monetary Fund, the European Union and the European Central Bank had to bailout certain failed European economies, but they also wanted these economies to restructure their economies based on the rules and the regulations of the IMF's "Washington Consensus". Here's an article by the English economist, Dr. John Williamson, which had coined that term as a way to disapprove of the policies that the IMF had implemented in many countries. In Greece, the Troika have demanded the exact same policies as John Williamson had lambasted in his article, especially when it comes to privatization of state industries. This leads to an interesting situation in Greece, where the bloated public sector has been connected to previous political election campaigns of both the major Greek parties as a way of institutionalizing corruption through vote purchasing. The anger of the crowds could be linked to these new policies which should have goals of liberating the Greek economy from the malaise of having an extremely unproductive and corrupt public sector. This has not really worked in Greece as it is very difficult to get rid of the old culture, plus the downward spiral of the Greek economy, which has been exacerbated by the cuts in benefits for ordinary citizens.
The crisis has caused tremendous hardship for many of the normal members of Greece with sharp increases in unemployment, cuts in state spending on welfare and on healthcare, reduction in the state infrastructure and a massive program of privatization. This has not just led to a breakdown in the Greek economy, but also numerous other social problems. Over 25% of Greeks are unemployed, with youth unemployment at 50% of above and many talented Greeks are moving out of Greece to find a more high-paying and desirable job within the Eurozone and in countries such as the United States. There has also been a tremendous breakdown in the normal social order, with countless people living on the streets, rummaging through trash cans to find out and the official poverty rate has increased to 45% by some estimates. Here's an extremely glaring chart that I found on Zero Hedge categorizing the tremendous poverty that has been accelerated acutely by the austerity that has been imposed on the Greece by the Troika:
 From this chart, we can talk about the very sharp and very acute increase in poverty that Greece has suffered ever since the start of the financial crisis. There has been reports of a huge resurgence of crime and lawlessness in Greece, which radical political groups such as the anarchists, the fascist Golden Dawn and some say, the current government, Syriza, have all seized the opportunity to increase their following. There have been countless numerous riots and incidents where there have been clashes between the different political elements in Greece. By browsing the internet and YouTube, you will be able to see these many incidents that has happened in a very unsettled and impoverished country. The radical leftists of the Syriza party have seized upon this crisis and by promoting an anti-austerity, pro-stimulus policy program, they have made the rest of the world look at that with a wary eye.
The Recent Election of Syriza and Current Situation
With the rather explosive situation in Greece, the radical leftists of the Syriza party was able to defeat the Troika's favored political party, the mainstream conservative party of the New Democracy. With this election of the Syriza, there has been a tremendous amount of both media coverage in what Alexis Tsipras and the radical Syriza might offer for the country. Here are two articles on Syriza: one that talks about the Syriza intellectuals that were educated in British universities and another on the roots of Alexis Tsipras. What's interesting from this particular situation is the clash between the leftist ideologues within the Syriza party, such as the Finance Minister, and the European finance and banking bureaucrats. Ever since the situation, Syriza has overturned many of the Troika's economic policies, such as the reduction of public sector workforce, the privatization of key publicly held companies and most importantly, they want to overturn the Troika's loan and debt policies. Alexis Tsipras has declared the end of the crippling austerity that the reforms have caused in Greece, but will face a tough battle and an intense clash with the authorities that have been dictating the terms of the Greek economy for the last 5-6 years.
Within the election of Syriza, financial markets at first reacted negatively to the possibility that Syriza would do great harm to the reform process that the Troika had implemented on the Greek economy, but now it has emerged that the European Central Bank will most likely dictate the terms to the Greek government. The Greek government had hoped to renegotiate the terms of the bailout package and the other economic terms that the Troika had implemented on Greece, but it looks like Alexis Tsipras and the Syriza have not completely backtracked from their strong anti-austerity rhetoric. Despite the fact that the European monetary authorities have a strong stranglehold on the Greek government's ability to operate as they had originally promised, they have found little common ground between them and the monetary authorities of countries like Germany. According to a recent article, Greece has been isolated in a previous meeting of finance ministers just before the Eurogroup meeting that will take place on Feb. 11th, which will be an important meeting in which the new Greek authorities will put forth a proposal that they want to be implemented in order to save their country from actually going bankrupt. With this meeting, Alexis Tsipras has just set up a clash with these ministers after laying out concrete plans to end the reforms that the Troika had implemented, especially the crippling austerity that has trapped millions of Greeks into long-term poverty. It will be a very interesting next couple of months for those who will be following how this interferes with the financial markets.
Possible Results and Possible Macroeconomic Effects
I believe that a Greek default and a Grexit of the euro are both entirely impossible. A more realistic solution to this confrontation is a negotiated write-offs of small amounts of Greek debt, while still not solving the problems in the structure of the economic institutions within Greece. Greece will still be continued to be saddled with massive public debt, institutional corruption and an extremely inefficient public sector. To improve the situation in Greece, there must be a change in how Greece functions as a democratic country. There needs to be more transparency in how the bureaucracy is managed, as debts could be potentially saved without resorting to drastic privatization or the massive public sector layoffs. I still don't believe that the institutional corruption or the entrenched political interests within Greece could be fixed overnight, since the new Syriza government wants a return to the statist government that promotes 'social justice' versus an economic model that promotes business growth. I believe that they will be able to get some debt concessions, but it does not address the long-term debt issues that Greece will have to face. The new Syriza government and the European monetary authorities will most likely end up kicking the can down the road.
There are many possible solutions and results that could come from this particular and interesting situation that Greece is facing, not just against its creditors, the Troika and the financial markets, but also against the underlying principles of liberal economics that has been prevalent throughout the world since the 1980s. There has been a resurgence of a previous dominant Keynesian thought in economic thought that has expanded beyond the confines of the New Keynesians and the followers of Paul Samuelson's neoclassical synthesis. I believe the election of Syriza in Greece will continue to trigger the resurgence of left Keynesian economic thought throughout the world, but also other left wing alternatives that might spurn the IMF's Washington Consensus and the general Monetarist and New Keynesian approaches to economic policy. I also believe we could potentially see the development of new economic models to explain the problems that countries such as Greece went through. Maybe there are possible solutions that could be utilized without the pitched ideological battles that has raged within the European community and beyond. I think there are a tremendous sets of new data that could be extrapolated from this particular situation and that data could be analyzed from the resulting resolution to the Greek crisis.
Debt Situation Background and the Economic Crisis
The debt crisis in Greece had started even before the 2007-2008 Global Financial Crisis with the entrance of Greece into the Eurozone and the overspending that occurred during the Olympics was blamed for the current debt crisis that had its seeds all the way back in 2004. While the Olympic Games was one of the many financial debacles that the Greek government has had in the last two decades, I would say it compares nowhere to the other pressing problems that led up to their debt implosion that occurred after the Global Financial Crisis.
A combination of a corrupt government bureaucracy that struck shady back room deals, a culture of endemic tax evasion and a burdensome public sector led to one of the most serious debt crises that any country has faced. It has been said that the corruption of Greek officialdom led Greece into the Eurozone by utilizing the services of Goldman Sachs to make their debt situation comfortable enough for the not as corrupt European bureaucrats to let Greece into the European Union. The mistake of letting one of the most corrupt nations in Europe to enter the Eurozone was compounded by the fact that much of this debt could have avoided if Greece undertook an immense political restructuring program that changed the way politics in Greece had been operating. From the bribes that the officials had extracted from the Greek taxpayers in order to bribe corrupt European Union officials to the bribes that Greek political parties had handed out in public sector jobs led to one of the worst possible economic environments in all of Europe. The public also engaged in one of the most institutionalized tax evasion schemes in the world. Here are two articles that explain the tax evasion problem that had plagued Greece: One published by the Economist and another by the New Yorker. The Greeks had also simply been living way beyond their means for a long time with the government deficit financed growth and when the financial crisis had hit the country, the entire corrupt Greek political and economic system fell apart.
The US economic crisis caused a huge breakdown in the global debt pyramid that had partially relied on the US mortgage-backed securities for further growth. With the entire debt pyramid collapse, there it unleashed an onslaught of bad debt and bad loans. It triggered a tidal wave of debt crises around in Europe and the worst basket case example in the Hellenic country of Greece. Countries like Greece that had largely been living beyond their means through cheap interest rates that the Eurozone had brought. Through years of unnatural interest rates and a horribly mismanaged national economy, Greece paid the ultimate price for being in the same economic zone with countries like Germany. The Greeks had to be bailed out several times and here's an article from 2012 that described the situation in Greece 3 years ago.
The International Lenders and Greece
The 'Troika' of the International Monetary Fund, the European Union and the European Central Bank had to bailout certain failed European economies, but they also wanted these economies to restructure their economies based on the rules and the regulations of the IMF's "Washington Consensus". Here's an article by the English economist, Dr. John Williamson, which had coined that term as a way to disapprove of the policies that the IMF had implemented in many countries. In Greece, the Troika have demanded the exact same policies as John Williamson had lambasted in his article, especially when it comes to privatization of state industries. This leads to an interesting situation in Greece, where the bloated public sector has been connected to previous political election campaigns of both the major Greek parties as a way of institutionalizing corruption through vote purchasing. The anger of the crowds could be linked to these new policies which should have goals of liberating the Greek economy from the malaise of having an extremely unproductive and corrupt public sector. This has not really worked in Greece as it is very difficult to get rid of the old culture, plus the downward spiral of the Greek economy, which has been exacerbated by the cuts in benefits for ordinary citizens.
The crisis has caused tremendous hardship for many of the normal members of Greece with sharp increases in unemployment, cuts in state spending on welfare and on healthcare, reduction in the state infrastructure and a massive program of privatization. This has not just led to a breakdown in the Greek economy, but also numerous other social problems. Over 25% of Greeks are unemployed, with youth unemployment at 50% of above and many talented Greeks are moving out of Greece to find a more high-paying and desirable job within the Eurozone and in countries such as the United States. There has also been a tremendous breakdown in the normal social order, with countless people living on the streets, rummaging through trash cans to find out and the official poverty rate has increased to 45% by some estimates. Here's an extremely glaring chart that I found on Zero Hedge categorizing the tremendous poverty that has been accelerated acutely by the austerity that has been imposed on the Greece by the Troika:
The Recent Election of Syriza and Current Situation
With the rather explosive situation in Greece, the radical leftists of the Syriza party was able to defeat the Troika's favored political party, the mainstream conservative party of the New Democracy. With this election of the Syriza, there has been a tremendous amount of both media coverage in what Alexis Tsipras and the radical Syriza might offer for the country. Here are two articles on Syriza: one that talks about the Syriza intellectuals that were educated in British universities and another on the roots of Alexis Tsipras. What's interesting from this particular situation is the clash between the leftist ideologues within the Syriza party, such as the Finance Minister, and the European finance and banking bureaucrats. Ever since the situation, Syriza has overturned many of the Troika's economic policies, such as the reduction of public sector workforce, the privatization of key publicly held companies and most importantly, they want to overturn the Troika's loan and debt policies. Alexis Tsipras has declared the end of the crippling austerity that the reforms have caused in Greece, but will face a tough battle and an intense clash with the authorities that have been dictating the terms of the Greek economy for the last 5-6 years.
Within the election of Syriza, financial markets at first reacted negatively to the possibility that Syriza would do great harm to the reform process that the Troika had implemented on the Greek economy, but now it has emerged that the European Central Bank will most likely dictate the terms to the Greek government. The Greek government had hoped to renegotiate the terms of the bailout package and the other economic terms that the Troika had implemented on Greece, but it looks like Alexis Tsipras and the Syriza have not completely backtracked from their strong anti-austerity rhetoric. Despite the fact that the European monetary authorities have a strong stranglehold on the Greek government's ability to operate as they had originally promised, they have found little common ground between them and the monetary authorities of countries like Germany. According to a recent article, Greece has been isolated in a previous meeting of finance ministers just before the Eurogroup meeting that will take place on Feb. 11th, which will be an important meeting in which the new Greek authorities will put forth a proposal that they want to be implemented in order to save their country from actually going bankrupt. With this meeting, Alexis Tsipras has just set up a clash with these ministers after laying out concrete plans to end the reforms that the Troika had implemented, especially the crippling austerity that has trapped millions of Greeks into long-term poverty. It will be a very interesting next couple of months for those who will be following how this interferes with the financial markets.
Possible Results and Possible Macroeconomic Effects
I believe that a Greek default and a Grexit of the euro are both entirely impossible. A more realistic solution to this confrontation is a negotiated write-offs of small amounts of Greek debt, while still not solving the problems in the structure of the economic institutions within Greece. Greece will still be continued to be saddled with massive public debt, institutional corruption and an extremely inefficient public sector. To improve the situation in Greece, there must be a change in how Greece functions as a democratic country. There needs to be more transparency in how the bureaucracy is managed, as debts could be potentially saved without resorting to drastic privatization or the massive public sector layoffs. I still don't believe that the institutional corruption or the entrenched political interests within Greece could be fixed overnight, since the new Syriza government wants a return to the statist government that promotes 'social justice' versus an economic model that promotes business growth. I believe that they will be able to get some debt concessions, but it does not address the long-term debt issues that Greece will have to face. The new Syriza government and the European monetary authorities will most likely end up kicking the can down the road.
There are many possible solutions and results that could come from this particular and interesting situation that Greece is facing, not just against its creditors, the Troika and the financial markets, but also against the underlying principles of liberal economics that has been prevalent throughout the world since the 1980s. There has been a resurgence of a previous dominant Keynesian thought in economic thought that has expanded beyond the confines of the New Keynesians and the followers of Paul Samuelson's neoclassical synthesis. I believe the election of Syriza in Greece will continue to trigger the resurgence of left Keynesian economic thought throughout the world, but also other left wing alternatives that might spurn the IMF's Washington Consensus and the general Monetarist and New Keynesian approaches to economic policy. I also believe we could potentially see the development of new economic models to explain the problems that countries such as Greece went through. Maybe there are possible solutions that could be utilized without the pitched ideological battles that has raged within the European community and beyond. I think there are a tremendous sets of new data that could be extrapolated from this particular situation and that data could be analyzed from the resulting resolution to the Greek crisis.
Thursday, January 22, 2015
Beginning of escalation of a currency war between Europe and the rest of the world?
The European Central Bank's upcoming quantitative easing plans has been headline business news for the last couple of days, but today the ECB has finally announced the measures that they will pursue in the coming months. has decided to pursue very aggressive easing policies that will surely affect the markets for the coming years. In pursuing an aggressive bond repurchasing program of upwards of 60 million euros per month, the ECB hopes to curb deflation that has hit the European Union's economy. In the introduction statement to the press conference, the President of the ECB, Mario Draghi, has decided to explain these particular measures. Draghi mentioned that the ECB wants this process to continue until they can reach the benchmark inflation rate of 2% in the European Union and that these measures will continue until the end of 2016. To fully understand the full consequences of this program, we can relay to my last article where I had mentioned the massive expansion of the Chinese M2 money supply. I think it will create a tsunami flood of cheap money that will flood the markets, which will further decrease the value of the euro versus other major currencies. Here are several charts that feature euro versus the two other major currencies.
Euro to US Dollar

Euro to Chinese Yuan
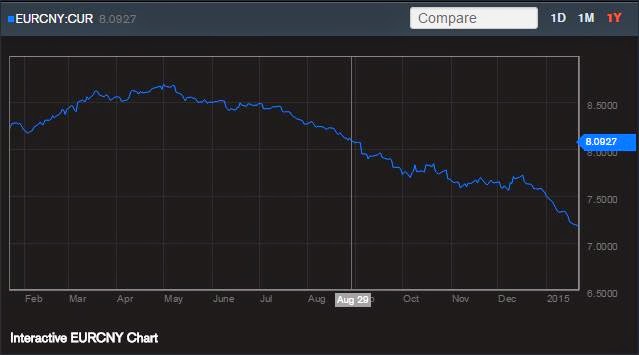
As we can see from this chart, the euro has fallen tremendously in the last year or so, from various other factors such as a weak European economy. The bond repurchasing program might have an interesting effect on its currency competitors. It might led to similar actions by the United States, by China, by the United Kingdom and other major central banks in order to promote export/import competitiveness. The start of Abenomics in Japan and this move by the European Central Bank has led to talk of more quantitative easing and more currency devaluations. I believe that the currency wars have just started between the major nations, while it will also lead to more people placing their assets into safe havens such as Switzerland. The Swiss might think twice about de-pegging their currency once again against these devalued major currencies...
(Here's a good and short summary article on the history of recent Swiss monetary history.)
Euro to US Dollar
Euro to Chinese Yuan
As we can see from this chart, the euro has fallen tremendously in the last year or so, from various other factors such as a weak European economy. The bond repurchasing program might have an interesting effect on its currency competitors. It might led to similar actions by the United States, by China, by the United Kingdom and other major central banks in order to promote export/import competitiveness. The start of Abenomics in Japan and this move by the European Central Bank has led to talk of more quantitative easing and more currency devaluations. I believe that the currency wars have just started between the major nations, while it will also lead to more people placing their assets into safe havens such as Switzerland. The Swiss might think twice about de-pegging their currency once again against these devalued major currencies...
(Here's a good and short summary article on the history of recent Swiss monetary history.)
Subscribe to:
Posts (Atom)